




Financing
How much does a bigger down payment save? The math on every ₪10,000
November 1, 2026

The simple math: ₪10,000 less financed
A down payment is the part of the car's price you pay up front, so it doesn't go into the loan. If we isolate ₪10,000 and calculate it as financing over 100 payments, the default term in the calculator on the site, at an illustrative CPI-linked rate of 3.9% and an assumed CPI rise of 5% a year, the payment on it comes to about ₪142 a month.
And from the other direction: every ₪10,000 paid as a down payment takes around ₪142 off the expected monthly payment. Over 100 payments, the same ₪10,000 would have cost you about ₪14,200, which means that in this example every ₪10,000 of down payment saves about ₪4,200 in interest.
To work this out yourself for any amount, divide the down payment by 10,000 and multiply by 142. A down payment of ₪25,000, for example, takes about ₪355 off the monthly payment under these conditions.
Why it works at any price
At the same rate and over the same term, the amount financed and the monthly payment move in direct proportion: ₪10,000 less financed takes the same amount off the payment, whether the car costs ₪100,000 or ₪250,000. That makes it easy to work out in your head: a down payment of ₪20,000 is about ₪285 less a month, ₪30,000 is around ₪425, and so on.
This is also the number shown on the tip card on the financing page. There it is calculated from the illustrative rate shown on the site at that moment, so if the illustrative rate changes, the number on the card will update with it.
An example on a whole car
Personalized car financing with a monthly payment that fits you
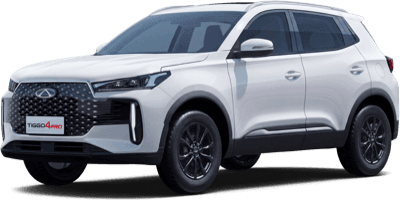
₪1,400 / monthSay a new car priced at ₪150,000, financed over 100 payments:
- No down payment: you finance ₪150,000. The payment is about ₪2,130 a month, and the total interest about ₪63,000.
- A down payment of ₪30,000: you finance ₪120,000. The payment is about ₪1,700 a month, and the total interest about ₪50,400.
- A down payment of ₪50,000: you finance ₪100,000. The payment is about ₪1,420 a month, and the total interest about ₪42,000.
In this example, a down payment of ₪50,000 takes about ₪710 off every payment and about ₪21,000 off the total interest.
The number changes with the term and the rate
The ₪142 holds under the conditions of the example. Under other conditions the number moves:
- Over 72 payments: every ₪10,000 of down payment takes about ₪180 off the payment and saves about ₪2,900 in interest.
- On a used car, at an illustrative CPI-linked rate of 5.9% and over 100 payments: about ₪153 less a month and about ₪5,300 less interest for every ₪10,000.
Note the difference: over a short term the down payment has a bigger effect on the monthly payment, but the interest saving is smaller, because the money would have stayed in the loan for less time.
Down payment and term work together
A down payment lowers the monthly payment, and shortening the term raises it. Combining the two lets you lower the total interest without the payment running away from your budget. On the same ₪150,000 car, a down payment of ₪30,000 over 72 payments brings the payment to about ₪2,160 a month and the total interest to about ₪35,300, compared with about ₪63,000 with no down payment over 100 payments.
And if the money only arrives after you've already started paying? You can ask the lender about partial early repayment. Its terms and fees are set in the loan agreement and vary between lenders.
How much should you put down?
A high down payment makes the financing cheaper, but the right size of down payment depends on your situation. A few things to weigh before deciding:
Don't empty your safety net
Money set aside for emergencies is better left available. If you need money urgently after putting all your savings into the down payment, you may end up paying more for it than the interest you saved.
Remember the costs of purchase day
The prices on the site do not include licensing fees, ownership transfer, add-ons and accessories, and on top of these there is insurance as well. It's worth setting aside an amount for them before you settle on the size of the down payment, so you don't reach delivery day with no margin.
A down payment that doesn't come from your account
If you have a car, its value can serve as the down payment instead of money from your savings, and by the same math every ₪10,000 of the car's value lowers the payment exactly like ₪10,000 in cash. You can also combine the two: part of the down payment from the trade-in and part in cash, whatever suits you. Get a trade-in offer and see how much your current car adds to the deal.
And what if there's no down payment at all?
The calculator on the site starts from a 0% down payment, and in some cases full or especially high financing can be considered, subject to the lender's approval, your credit data and the type of car. Even then, any amount you can add as a down payment will lower the payment by the same math.
In summary
The math of a down payment is simple: under the conditions of the example, every ₪10,000 takes around ₪142 off the monthly payment and about ₪4,200 off the total interest. In the financing calculator you can move the down payment amount and see the effect right away, on a car from the catalog or on the monthly payment that suits you. When the numbers work out, you can submit a request for an initial eligibility check.
All amounts in this article are for illustration only and are rounded. The calculation adds the illustrative rate and the CPI assumption into a single annual rate, as the calculator on the site does; in an actual CPI-linked loan, the principal and the payment are updated according to the index published each month. The rate, the payment and the financing terms are set by the lender after an eligibility check and are subject to its approval, and do not include a file-opening fee or other costs.
Need help or advice?
Contact us about anything - leave your details or call the branch directly
Get in touch about anything
Leave your details or call the branch directly at 03-652-9604